Tại sao lại mua cổ phiếu

  • Bắt đầu Bắt đầu enzonado
  • Ngày bắt đầu Ngày bắt đầu

enzonado

Yếu sinh lý
Tụi bay cho tao hỏi bản chất của việc mua cổ phiếu là để đầu cơ hay đầu tư.
Tao thấy tụi nó cứ chém gió là mua cổ phiếu để đầu tư. Đầu tư ở đây nghĩa là gì nhỉ - ăn cổ tức chăng.
Tao lấy ví dụ thằng techcombank.
Gần 10 năm qua, năm nào lợi nhuận cũng hàng ngàn tỉ nhưng tụi nó vẫn ko chia cổ tức (cả tiền và cổ phiếu). Trong khi đó giả cổ phiếu thì vẫn cứ giảm.
Tụi nó có bài là để tăng vốn chủ sở hữu. tăng vốn điều lệ.
Chuyện gì sẽ xảy ra khi nó cứ tăng vốn thế nhỉ. Như vậy những người đầu tư sẽ ko có lợi nhuận, (ko có cổ tức). chưa kể đến việc giả cổ phiếu còn bị giảm. Vậy tại sao bọn nhà đầu tư nước ngoài, và các quỹ nó vẫn cứ mua nhỉ.
 

enzonado

Yếu sinh lý
Vậy sao các quỹ đầu tư tụi nó lại mua nhỉ.
Vì mấy thằng chủ chắn chắn sẽ ôm hết mẹ quyền quyết định rồi. Bọn quỹ đầu tư mua vào cũng éo có quyền gì.
Như vậy tụi nó tuyên truyền các kiểu, các khóa học tài chính các kiểu cũng khác éo gì lùa anh em vào để úp bô đâu
 

Thích Thịt Bò

Tao là gay
Vậy sao các quỹ đầu tư tụi nó lại mua nhỉ.
Vì mấy thằng chủ chắn chắn sẽ ôm hết mẹ quyền quyết định rồi. Bọn quỹ đầu tư mua vào cũng éo có quyền gì.
Như vậy tụi nó tuyên truyền các kiểu, các khóa học tài chính các kiểu cũng khác éo gì lùa anh em vào để úp bô đâu
Tầm nhìn 5 10 năm nó khác 5 10 ngày. Quan trọng là có đủ tiền theo k thôi
 

enzonado

Yếu sinh lý
Umh. tao thấy cũng ko đúng lắm.
Giả sử như thằng vietcombank. 1 trong những thằng đc coi là làm ăn ngon đi nhé.
Lịch sử 10 năm qua của nó là cứ cách 1 năm chia cổ tức bằng cổ phiếu, rồi 1 năm sau lại chia bằng tiền mặt.
cổ tức tiền mặt thì vào 1k/1 cổ, còn cổ tức cổ phiếu thì tầm 20%
Giả sử tao có 1000 cp. (giá hiện tại là 80k. tầm 80 củ)

. Năm 1 => 1200 CP
. Năm 2 => 1,2 tr
. Năm 3 => 1440 CP
. Năm 4 => 1,440 tr
. Năm 5 => 1728 CP
. Năm 6 => 1,728 tr
. Năm 7 => 2073 CP
. Năm 8 => 2,073 tr
. Năm 9 => 2487 CP
. Năm 10 => 2,487 tr

======> Tổng sau 10 năm mình có khoảng 9 củ tiền lãi.
Vậy là bỏ 80tr. sau 10 năm mới đc có 9 củ. tính ra éo đc 1% / năm.
Thật vl
 

TracyV

Yếu sinh lý
Nhỏ lẻ thì là đầu cơ chứ chả có đầu tư cái mẹ gì cả. Vì nhỏ lẻ mua cổ phiếu vào bản chất mục đích 100% là muốn bán được giá để kiếm lời. Khi nào mục tiêu là vào danh sách cổ đông lớn thì hẵng gọi là đầu tư.
 

PinkS

Yếu sinh lý
Oh. T cũng đ hiểu gì cả. Ae nào có kiến thức chia sẻ đi. Nếu kiểu đầu cơ sao k phang con lô nhỉ?
 

enzonado

Yếu sinh lý
Nhỏ lẻ thì là đầu cơ chứ chả có đầu tư cái mẹ gì cả. Vì nhỏ lẻ mua cổ phiếu vào bản chất mục đích 100% là muốn bán được giá để kiếm lời. Khi nào mục tiêu là vào danh sách cổ đông lớn thì hẵng gọi là đầu tư.
Vậy là trước nay. mấy cái clip. mấy cái thầy nọ thầy kia. thậm chí mấy cái sách vở học trong trường lớp tụi nó lùa gà mẹ hết. Đúng là sách vở viết ra là để phục vụ mấy thằng tư bản. vì tao thấy người được lợi cuối cùng là mấy thằng chủ doanh nghiệp chứ đéo đến lượt mấy thằng mua cổ phiếu.
Thằng trên kia nói đúng. thế này có khi phang mẹ lô thấy còn trắng đen luôn. chứ như mấy cái mẹ tụi nó toàn lùa mình.
 

TracyV

Yếu sinh lý
Kể cả quỹ "đầu tư" thì cũng gọi là đánh bạc chứ đầu tư cái ccc gì. Năm vừa rồi đầy quỹ đầu tư vốn nước ngoài lỗ sặc máu đít đó. Tất nhiên là với quỹ đầu tư thì chúng nó có thêm một mục đích khác là bắt tay với doanh nghiệp và công ty chứng khoán để làm giá cổ phiếu.
Còn nếu đầu tư thật theo quy mô lớn thì nó còn có một số ràng buộc (như là cam kết không bán cổ phiếu trong vòng bao nhiêu năm)
 

boyhoangdai07

Tiến sĩ
Vậy sao các quỹ đầu tư tụi nó lại mua nhỉ.
Vì mấy thằng chủ chắn chắn sẽ ôm hết mẹ quyền quyết định rồi. Bọn quỹ đầu tư mua vào cũng éo có quyền gì.
Như vậy tụi nó tuyên truyền các kiểu, các khóa học tài chính các kiểu cũng khác éo gì lùa anh em vào để úp bô đâu
Quỹ nó mua lúc thấp, xong nó lái lên để bán, cứ thế mà chén thôi, chết mấy ông nhỏ lẻ thôi
 

KiemTraBai

Yếu sinh lý
thị trường việt nam vẫn đang in distribution mode, nhóm nhỏ chạy cty nắm đa phần cổ phiếu, nó chỉ là mớ giấy thôi
tài sản nằm ở công ty holding rồi. nhìn FLC chẳng hạn, ngân hàng thu lại hết tài sản đảm bảo, cổ đông còn cái gì đâu
hầu hết cty trên sàn là như vậy
tại sao mua? nó như tại sao mua sổ xố, tại sao đánh đề ý, tại sao mua tờ giấy
 

boyhoangdai07

Tiến sĩ
thị trường việt nam vẫn đang in distribution mode, nhóm nhỏ chạy cty nắm đa phần cổ phiếu, nó chỉ là mớ giấy thôi
tài sản nằm ở công ty holding rồi. nhìn FLC chẳng hạn, ngân hàng thu lại hết tài sản đảm bảo, cổ đông còn cái gì đâu
hầu hết cty trên sàn là như vậy
tại sao mua? nó như tại sao mua sổ xố, tại sao đánh đề ý, tại sao mua tờ giấy
Mày nói đúng, giống kiểu chơi cờ bạc biết thua mà vẫn đâm đầu vào
Ai hỏi tại sao chơi thì đéo giải thích được
 

boyhoangdai07

Tiến sĩ
Vì hi vọng kiếm được ít tiền khi còn người ta bế tắc trong việc kiếm tiền ,thì người ta tìm đến những cái này
vì đ còn cửa nào chứ sao
gửi tiết kiệm thì lạm phát âm tiền
đất đai thì lùa rồi giã cho
vàng thì spread to mua cái là lỗ
Chuẩn, vì hiện cũng chẳng có kênh nào mà đầu tư kiếm tiền nên đành phải lao vào cổ phiếu thôi
BĐS giờ cũng chết mất ngáp rồi
 

KiemTraBai

Yếu sinh lý
Chuẩn, vì hiện cũng chẳng có kênh nào mà đầu tư kiếm tiền nên đành phải lao vào cổ phiếu thôi
BĐS giờ cũng chết mất ngáp rồi
bđs ôm lâu dài cũng phải trông, xui thì bị CPO mất. nhiều ng tranh chấp xong nhồi máu cơ tim đột quỵ
bđs còn nằm đến 2025 mới tạo đáy. có cửa xây nhà cho thuê thì tuần trước hẹo mất rồi, chưa hiểu luật mới sẽ như thế nào
 

KiemTraBai

Yếu sinh lý
LONDON & HO CHI MINH CITY, Vietnam--(BUSINESS WIRE)--Sep 25, 2023--
To avoid issuance of an acceleration notice, No Va Land Investment Group Corp. must engage with an Ad Hoc Group of international bondholders, comprising investors with a combined AUM in excess of USD15bn, holding over 75% of USD 300m convertible bonds, to negotiate a restructuring agreement in good faith. An acceleration notice would have a spiralling e!ect on other stakeholders; if unsecured creditors accelerate the debt to step to the front of the line, more senior (secured) creditors will likely accelerate, derailing the entire restructuring process underway with onshore creditors, risking bankruptcy. Furthermore, equity could be zeroed out, ceding control of the company to creditors.
The Trustee to No Va Land’s USD 300m convertible bonds, Bank of NY Mellon, has already issued multiple Event of Default notices, most recently on 17 July 2023, related to the missed coupon payment due 16 July 2023. Despite a process to negotiate a consensual restructuring in the wake of a forbearance agreement having been attempted, the Board of No Va Land has refused to engage with the group in good faith.
The case has implications for other Vietnamese conglomerates with debt trading at stressed levels and refinancing concerns. This is the first restructuring in the context of the Vietnam 2035 vision and government attempts to capitalise on the growing China + 1 strategy. The stalling of No Va Land’s restructuring almost certainly creates issues for other companies which are critical to the Vietnamese economy. This would seem entirely unsatisfactory for the government’s plans to achieve its ambitious GDP growth in 2H 2023, which will be reliant on foreign investment after GDP growth significantly slowed, to 3.7% in 1H 2023, from 8% in 2022.
The Ad Hoc Group, whose members have been significant investors in Vietnam over many years, are highly concerned about the prioritisation of onshore creditors over international investors. A failure to reach an agreement is significantly impacting Vietnam’s standing in the international financial market and damaging investor confidence in the country.
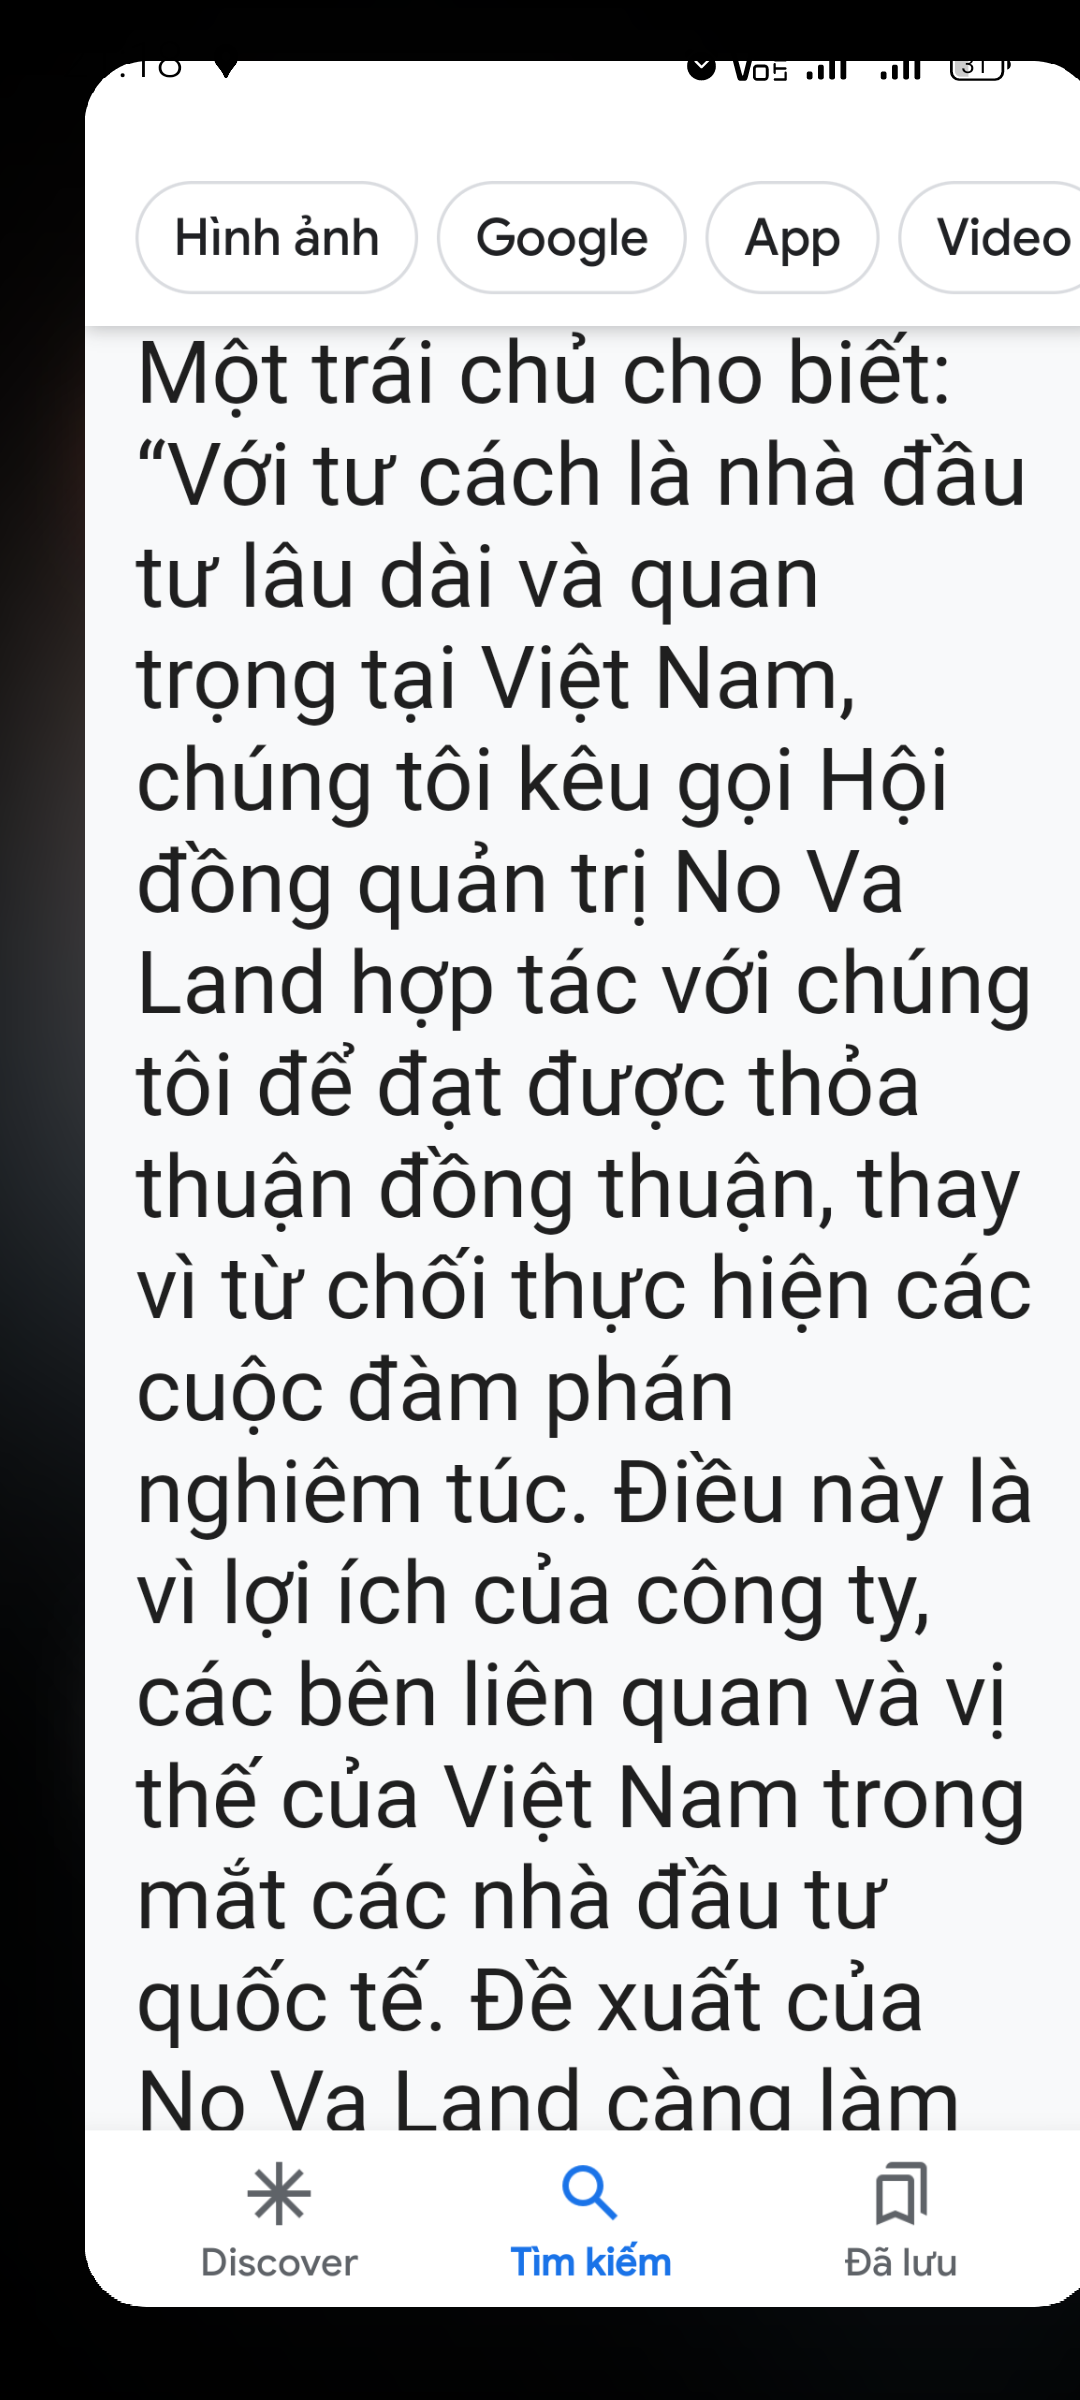
A bondholder said: “As long term and significant investors in Vietnam, we urge the Board of No Va Land to engage with us to reach a consensual agreement, rather than refusing to countenance serious negotiations. This is for the good of the company, its stakeholders and Vietnam’s standing among international investors. No Va Land’s proposal further erodes our confidence in the process, forcing us to consider an acceleration notice which would negatively impact creditors and likely wipe out equity. By negotiating with onshore investors while blatantly sidelining international investors, No Va Land is projecting the message that global investors will not be supported but overlooked in a default, which is not conducive to encouraging the FDI Vietnam needs to capitalise on the growing China + 1 investment strategy.”
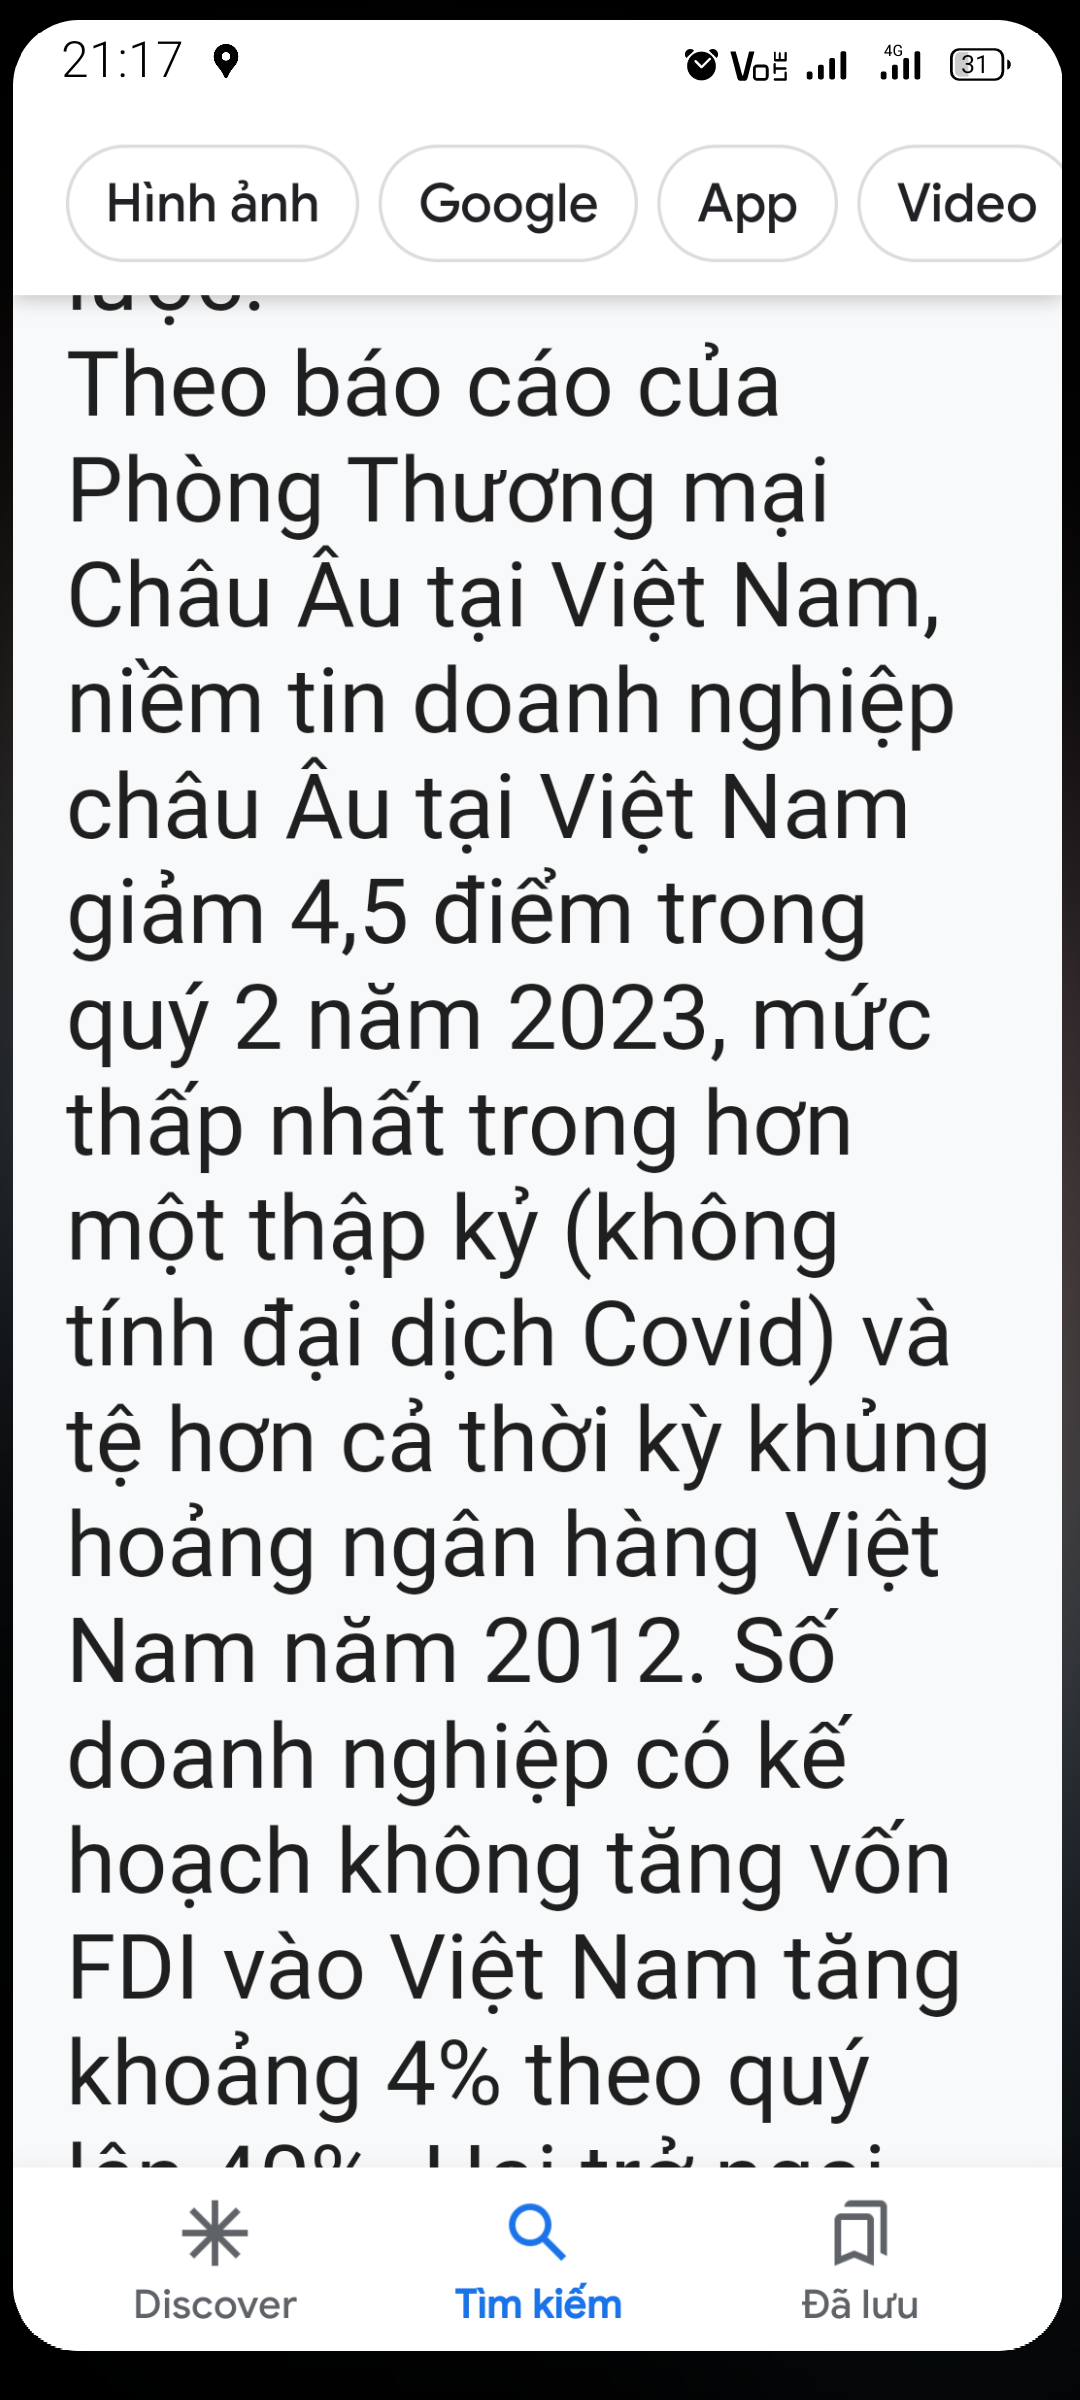
European business confidence in Vietnam dropped 4.5 points in Q2 2023, its lowest level in over a decade (excluding the Covid pandemic) and worse than during the Vietnam banking crisis of 2012, according to a report by the European Chamber of Commerce in Vietnam. The number of businesses who plan no increase in FDI in Vietnam rose c.4% QoQ to 40%. The top two obstacles cited to doing business are unclear rules and regulations and administrative issues and di"culties.
Continued Foreign Direct Investments into Vietnam are required to support the rapid capital expenditure to scale domestic infrastructure spending and this all needs to be underpinned by a functioning restructuring regime.


phanh

Yếu sinh lý
LONDON & HO CHI MINH CITY, Vietnam--(BUSINESS WIRE)--Sep 25, 2023--
To avoid issuance of an acceleration notice, No Va Land Investment Group Corp. must engage with an Ad Hoc Group of international bondholders, comprising investors with a combined AUM in excess of USD15bn, holding over 75% of USD 300m convertible bonds, to negotiate a restructuring agreement in good faith. An acceleration notice would have a spiralling e!ect on other stakeholders; if unsecured creditors accelerate the debt to step to the front of the line, more senior (secured) creditors will likely accelerate, derailing the entire restructuring process underway with onshore creditors, risking bankruptcy. Furthermore, equity could be zeroed out, ceding control of the company to creditors.
The Trustee to No Va Land’s USD 300m convertible bonds, Bank of NY Mellon, has already issued multiple Event of Default notices, most recently on 17 July 2023, related to the missed coupon payment due 16 July 2023. Despite a process to negotiate a consensual restructuring in the wake of a forbearance agreement having been attempted, the Board of No Va Land has refused to engage with the group in good faith.
The case has implications for other Vietnamese conglomerates with debt trading at stressed levels and refinancing concerns. This is the first restructuring in the context of the Vietnam 2035 vision and government attempts to capitalise on the growing China + 1 strategy. The stalling of No Va Land’s restructuring almost certainly creates issues for other companies which are critical to the Vietnamese economy. This would seem entirely unsatisfactory for the government’s plans to achieve its ambitious GDP growth in 2H 2023, which will be reliant on foreign investment after GDP growth significantly slowed, to 3.7% in 1H 2023, from 8% in 2022.
The Ad Hoc Group, whose members have been significant investors in Vietnam over many years, are highly concerned about the prioritisation of onshore creditors over international investors. A failure to reach an agreement is significantly impacting Vietnam’s standing in the international financial market and damaging investor confidence in the country.
A bondholder said: “As long term and significant investors in Vietnam, we urge the Board of No Va Land to engage with us to reach a consensual agreement, rather than refusing to countenance serious negotiations. This is for the good of the company, its stakeholders and Vietnam’s standing among international investors. No Va Land’s proposal further erodes our confidence in the process, forcing us to consider an acceleration notice which would negatively impact creditors and likely wipe out equity. By negotiating with onshore investors while blatantly sidelining international investors, No Va Land is projecting the message that global investors will not be supported but overlooked in a default, which is not conducive to encouraging the FDI Vietnam needs to capitalise on the growing China + 1 investment strategy.”
European business confidence in Vietnam dropped 4.5 points in Q2 2023, its lowest level in over a decade (excluding the Covid pandemic) and worse than during the Vietnam banking crisis of 2012, according to a report by the European Chamber of Commerce in Vietnam. The number of businesses who plan no increase in FDI in Vietnam rose c.4% QoQ to 40%. The top two obstacles cited to doing business are unclear rules and regulations and administrative issues and di"culties.
Continued Foreign Direct Investments into Vietnam are required to support the rapid capital expenditure to scale domestic infrastructure spending and this all needs to be underpinned by a functioning restructuring regime.

81407-dfcb1be65a57.png
 

phanh

Yếu sinh lý
LONDON & HO CHI MINH CITY, Vietnam--(BUSINESS WIRE)--Sep 25, 2023--
To avoid issuance of an acceleration notice, No Va Land Investment Group Corp. must engage with an Ad Hoc Group of international bondholders, comprising investors with a combined AUM in excess of USD15bn, holding over 75% of USD 300m convertible bonds, to negotiate a restructuring agreement in good faith. An acceleration notice would have a spiralling e!ect on other stakeholders; if unsecured creditors accelerate the debt to step to the front of the line, more senior (secured) creditors will likely accelerate, derailing the entire restructuring process underway with onshore creditors, risking bankruptcy. Furthermore, equity could be zeroed out, ceding control of the company to creditors.
The Trustee to No Va Land’s USD 300m convertible bonds, Bank of NY Mellon, has already issued multiple Event of Default notices, most recently on 17 July 2023, related to the missed coupon payment due 16 July 2023. Despite a process to negotiate a consensual restructuring in the wake of a forbearance agreement having been attempted, the Board of No Va Land has refused to engage with the group in good faith.
The case has implications for other Vietnamese conglomerates with debt trading at stressed levels and refinancing concerns. This is the first restructuring in the context of the Vietnam 2035 vision and government attempts to capitalise on the growing China + 1 strategy. The stalling of No Va Land’s restructuring almost certainly creates issues for other companies which are critical to the Vietnamese economy. This would seem entirely unsatisfactory for the government’s plans to achieve its ambitious GDP growth in 2H 2023, which will be reliant on foreign investment after GDP growth significantly slowed, to 3.7% in 1H 2023, from 8% in 2022.
The Ad Hoc Group, whose members have been significant investors in Vietnam over many years, are highly concerned about the prioritisation of onshore creditors over international investors. A failure to reach an agreement is significantly impacting Vietnam’s standing in the international financial market and damaging investor confidence in the country.
A bondholder said: “As long term and significant investors in Vietnam, we urge the Board of No Va Land to engage with us to reach a consensual agreement, rather than refusing to countenance serious negotiations. This is for the good of the company, its stakeholders and Vietnam’s standing among international investors. No Va Land’s proposal further erodes our confidence in the process, forcing us to consider an acceleration notice which would negatively impact creditors and likely wipe out equity. By negotiating with onshore investors while blatantly sidelining international investors, No Va Land is projecting the message that global investors will not be supported but overlooked in a default, which is not conducive to encouraging the FDI Vietnam needs to capitalise on the growing China + 1 investment strategy.”
European business confidence in Vietnam dropped 4.5 points in Q2 2023, its lowest level in over a decade (excluding the Covid pandemic) and worse than during the Vietnam banking crisis of 2012, according to a report by the European Chamber of Commerce in Vietnam. The number of businesses who plan no increase in FDI in Vietnam rose c.4% QoQ to 40%. The top two obstacles cited to doing business are unclear rules and regulations and administrative issues and di"culties.
Continued Foreign Direct Investments into Vietnam are required to support the rapid capital expenditure to scale domestic infrastructure spending and this all needs to be underpinned by a functioning restructuring regime.

81408-4317e060d8c2.png
 
Bên trên
X
telegram-icon
Tắt Quảng Cáo